Michael Burry read Anthropic’s IPO papers and came away calling the whole AI industry “catastrophically vulnerable”. The man who called 2008 has earned the right to be listened to. But I’ve been through the same S-1, and I think he’s half right. Here’s my reply.
Opinion, not financial advice. The featured image above is satire, not a real photo.
What Michael Burry actually said
According to the Economic Times, which cites a Business Insider report on his Tuesday Substack post, Burry zeroed in on three things in Anthropic’s S-1: huge spending commitments, slowing revenue growth and tangled ties with Big Tech.
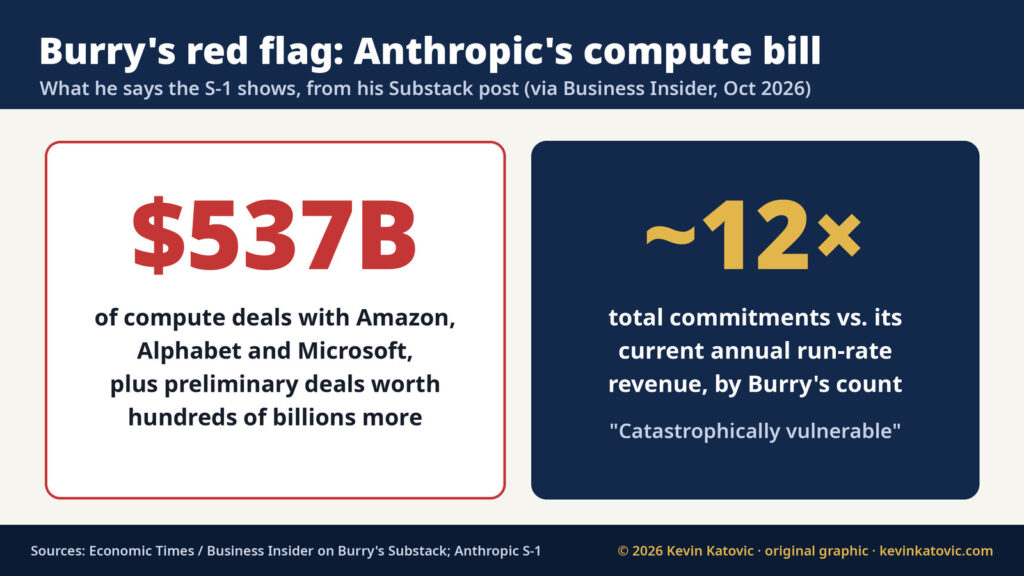
- The compute bill: about $537 billion of compute deals with Amazon, Alphabet and Microsoft, plus preliminary agreements worth hundreds of billions more with others such as SpaceXAI. By his math, total commitments run about 12 times Anthropic’s current annual run-rate revenue.
- His words: “This is not stated clearly in the S-1, and in my view it is the most deserved headline from it.” He added: “Overall slowing of growth is not attributed to a decline in tokenmaxxing, but I did not expect that to be mentioned.”
- His bigger call: earlier, on X, he wrote “For the benefit of humanity, the markets should tank hard and prevent the OpenAI and Anthropic IPOs.” He says the market is in a “denial” phase that could last six to nine months, and he’s been shorting AI-linked stocks.
There’s an old saying: torture the numbers long enough and they’ll confess to anything. Burry isn’t torturing them, though. The commitment number is real, and it’s the right thing to be nervous about.
Where Burry is right
I flagged the same problem when I first went through the filing. A company doesn’t sign up for more than half a trillion dollars of compute unless it expects revenue to keep climbing for years. If growth slows, those contracts don’t shrink with it. That’s the definition of fragile: fixed costs on one side, hoped-for revenue on the other.
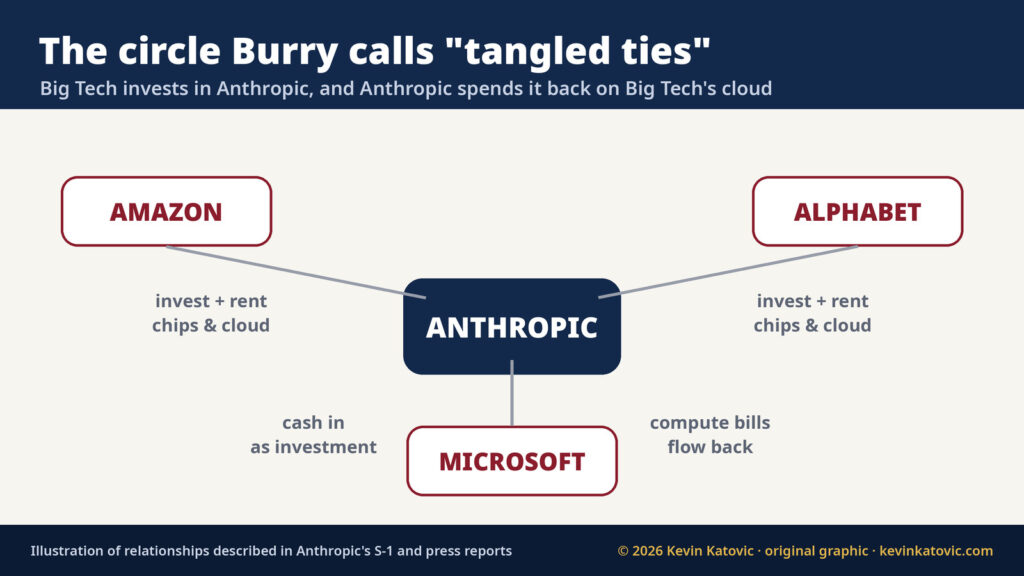
He’s also right that the relationships are tangled. Amazon, Alphabet and Microsoft all have money in Anthropic, and Anthropic spends a huge share of what it raises renting their chips and cloud. The money goes around in a circle. As I wrote in my Google stock post, I already think Alphabet’s ad income is inflated by click fraud. Now some of that same money is being recycled into an AI lab that pays it straight back to Google Cloud. That loop flatters everyone’s numbers until it stops.
What Burry leaves out
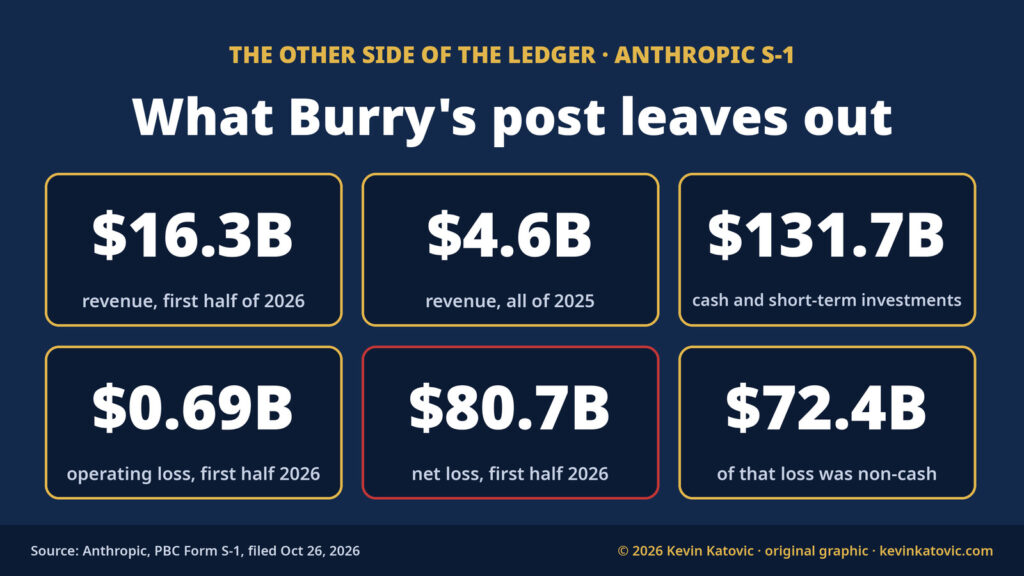
Here’s my problem with “catastrophically vulnerable.” The same S-1 shows a business that is growing faster than almost anything I’ve seen:
- Revenue: $16.3 billion in the first half of 2026, against $4.6 billion in all of 2025.
- Cash: $131.7 billion in cash and short-term investments at June 30, before a single IPO share is sold.
- The real loss: the scary $80.7 billion net loss is mostly paper. $72.4 billion of it was a non-cash fair-value charge on notes and SAFEs. The operating loss was about $693 million.
- Customers: more than 11,900 customers paying $100,000 or more a year.
Compute commitments are also spread over years, not due next quarter. Comparing a multi-year contract total to one year of revenue makes the number look worse than the cash flow does. I’d rather see the payment schedule by year than a single scary multiple.
My take: not a catastrophe, but not a free lunch
I’m not changing my ANT price prediction of about $97 a share. Burry is right that Anthropic has built a cost base that only works if AI demand keeps compounding. I just don’t think the S-1 shows a company on the edge. It shows a company with a lot of runway that has made a very big, very expensive bet.
What would change my mind:
- Revenue growth falling quarter over quarter in the S-1/A update.
- Big Tech partners pulling back on new investment while the compute bills stay the same.
- Any sign the commitments can’t be renegotiated or pushed out if demand cools.
- A price range that values ANT far above what the revenue can support.
Where the money really goes
If you want to understand Burry’s worry, follow the hardware. What a data center build really spends money on explains why these contracts are so big, and the cost of filling a 100 MW hall with AI servers puts real numbers on it. Over ten years, the total cost of owning an AI factory is where these commitments land. For the week’s other AI headlines, see this roundup of Gemini, GPT-Live and the rest. And if you’re pricing your own build, the AI Build Configurator does the math.
Michael Burry and Anthropic FAQ
What did Michael Burry say about Anthropic’s IPO?
In a Substack post reported by Business Insider and the Economic Times, Burry said Anthropic’s IPO filing shows the AI industry is “catastrophically vulnerable.” He pointed to about $537 billion of compute deals with Amazon, Alphabet and Microsoft, preliminary deals worth hundreds of billions more, slowing growth and tangled ties with Big Tech.
How big are Anthropic’s compute commitments?
Burry counts about $537 billion in compute purchase deals with Amazon, Alphabet and Microsoft, plus preliminary agreements with others such as SpaceXAI. He puts total commitments at roughly 12 times Anthropic’s current annual run-rate revenue.
Is Anthropic losing money?
Yes. The S-1 shows an $80.7 billion net loss for the first half of 2026, but $72.4 billion of that was a non-cash fair-value charge. The operating loss was about $693 million, on $16.3 billion of revenue, with $131.7 billion of cash and short-term investments.
What is Anthropic’s stock ticker?
Anthropic plans to list its Class A shares on the Nasdaq Global Select Market under the ticker ANT. The price range and share count had not been set when this was written.
Is Michael Burry shorting AI stocks?
Burry has said he is betting against AI-linked stocks and has warned of a sharp selloff. Anthropic is not public yet, so it cannot be shorted directly.
Sources: Economic Times, Oct 29, 2026, citing Business Insider on Burry’s Substack; Anthropic, PBC Form S-1 on SEC EDGAR.
Images: the featured image and the second image are illustrations, not real photos. The three charts are original graphics by Kevin Katovic. © 2026 Kevin Katovic, all rights reserved for the original graphics. To license one, email support@kevinkatovic.com.