Elon Musk says more than 200 neoclouds are headed for “guppy-level death and consolidation.” CoreWeave and Nebius dipped before the bell on Monday. He has a point about the debt. But take my official warning. As for the information from someone who just borrowed $40 billion to buy his own GPUs I think that level of insanity deserves a second read. Here is my response as I have a personal experience to judge quickly but remain factual and provide evidence. I tend to lose money when I bet against Elon like I did in SpaceX which obviously isn’t making many friends which is still below 150 a share.
What Musk actually said
Yahoo Finance’s Brian Sozzi reported this morning, October 26, 2026, that Musk posted on X that 200+ neoclouds, the newer cloud companies that mostly rent out GPUs for AI, will see “guppy-level death and consolidation.” Earlier this month he had already replied “Yikes” to a post about CoreWeave’s finances, which if you remember Cramer told us was his pick and to buy it.
His reasoning: debt markets are getting nervous about lending to companies whose sales come almost entirely from AI data centers. He contrasted that with SpaceX, which he says raised $40 billion in debt to buy GPUs because lenders could lean on stronger businesses like Starlink which would charge me $1,500 CND a mo just to replace my current level internet service.
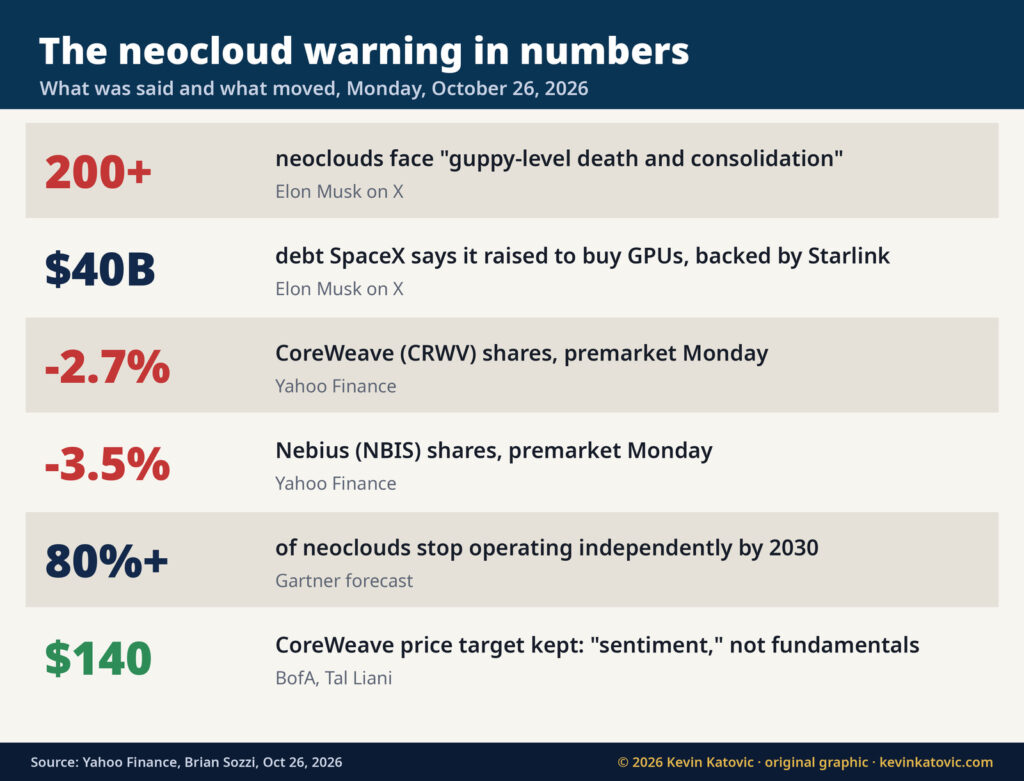
The market listened, a little. CoreWeave (CRWV) was down 2.7% and Nebius (NBIS) 3.5% in premarket trading, and CoreWeave’s bonds were already being sold on worries about an AI slowdown and its balance sheet.
Where he is right
The neocloud model is simple and fragile: borrow money, buy GPUs, rent them out, and hope the rent covers the loan before the chips go stale. A GPU that is cutting-edge today is a hand-me-down in two or three years. If the loan runs longer than the contract, or the contract walks away, the lender is left holding very expensive used hardware. Which remember goes hand in hand with the ” All in Operator ” and ” Pass Through ” option if you buy our Data Center Calculator understanding that option is clutch to neo cloud builders.
The customers are the other risk. A lot of that rental money comes from AI labs that are themselves losing fortunes. Look at how much money even the best-funded AI labs are burning and you start to see why a bond buyer would want a backstop that isn’t AI.
So no, I don’t think there is room for 200 independent GPU landlords. Gartner agrees: it forecasts that by 2030 more than 80% of neocloud providers will stop operating on their own, citing “cost pressure and a lack of a differentiating business model.” I sometimes remind you make believe is not always a naive bed partner but maybe commonplace in some other cultures that might be even described as disorganized thought in Canada.
But consider who is talking
Musk is not a neutral referee here. SpaceX is buying the same GPUs, from the same suppliers which might just be waiting to bleed anthropic which might just be another front for elon musk’s circle finance options. For the same AI demand. When the biggest new buyer in the market tells everyone the smaller buyers are doomed, that is also a sales pitch. It makes his own debt look safer and trust me he has some but its well hidden, and it pushes the cost of money up for his competitors. That doesn’t make him wrong. It just means his warning and his business plan are the same thing so the pentagon to anthropic to elon musk might be the circle finance your watching.
Wall Street isn’t fully buying it either. Bank of America analyst Tal Liani told Yahoo Finance the CoreWeave sell-off “is more sentiment driven. This is not about fundamentals,” said its ability to pay its debt is not the issue, and kept his $140 price target.
Guppy or shark: who survives
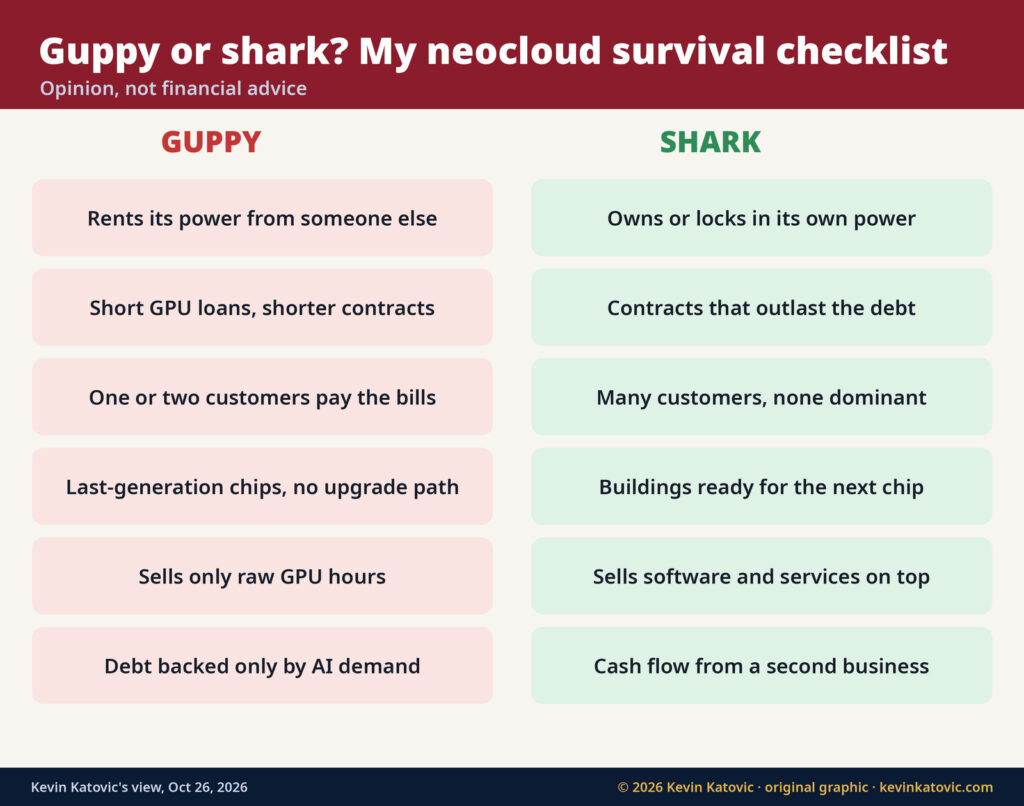
Consolidation is not the same as computers being switched off. When a guppy gets eaten, the building, the power hookup and the racks don’t disappear. They get a new owner at a better price. So the real question is who does the eating. My checklist:
- Power first. The scarce thing in 2026 is not chips, it is electricity and a grid connection. A company that owns or has locked in its own megawatts is a buyer, not a target. If you want to see why, look at what an AI hall needs beyond the GPUs themselves.
- Contracts longer than the debt. If the customer is signed up for longer than the loan runs, the lender sleeps at night.
- More than one big customer. One or two tenants paying most of the bills is how a shark turns into a guppy overnight.
- Buildings ready for the next chip. Each new GPU generation runs hotter and needs more power per rack. Halls that can take liquid cooling and denser racks keep their value after the chips age out.
- Something to sell besides raw GPU hours. Software, managed services and inference platforms make customers stickier.
- A second source of cash. This is Musk’s real point, and it is fair: SpaceX can borrow against Starlink. A pure GPU landlord can only borrow against hope. But didn’t he do that already? Since Elon needs real customers to gain income obviously there is only so much StarLink income can be syphoned before expansion into Mobile Towers and Cellular might be too difficult but the only thing on his mind perhaps.
Most of that list is decided before the first server ever arrives: site, power, cooling and how much was spent. The companies that will get eaten are the ones that never knew where every dollar in a server building actually goes and borrowed against best-case numbers. Jensen tried explaining how he provides his own capital for new projects but few people perhaps are listening.
My take
Musk is right that most neoclouds won’t survive on their own but consider this if I am myself propping up a failing business it might be because there is a multiple on my life. The fish metaphor is about debt, but the real filter is power and boy do I think I deserve some after suffering on this government income for 15 years. AI demand is not going away. What is going away is the idea that you can borrow your way into the business without owning the hard part.
If I were building today, I would run my own numbers before a lender runs them for me, and I would size the whole build, power, cooling and GPUs, in the AI Build Configurator before signing anything. Be the shark. Or at least know exactly how big a fish you are.
This is my opinion, not financial advice. Stocks of companies like CoreWeave and Nebius can move sharply, and you can lose money while sure Cramer might be right since GoldMan can leverage the power of the many to service the debts of the few ha ha? He is going to respond at madmoney@cnbc.com just one time maybe? I doubt it just like all the others……
Neocloud FAQ
What is a neocloud?
A neocloud is a newer cloud company that mostly rents out GPU computing power for AI, rather than offering the full menu of services that Amazon, Microsoft or Google sell. CoreWeave and Nebius are the best-known public examples.
What did Elon Musk say about neoclouds?
In an X post reported by Yahoo Finance on October 26, 2026, Musk said 200+ neoclouds will face guppy-level death and consolidation, arguing that debt markets are wary of companies whose revenue depends almost entirely on AI data centers. I’ll be honest with you, I really do need one of these chowder heads to reply to one of my emails so I can prove your not all losers and thieves and spys. But I remind you why make sense? Why would I be interested in all these local facilities in BC that BCHYDRO already baked in a anti-competitive clause on. What do you think I’m a true Genius or something?
Why did CoreWeave and Nebius stock fall?
CoreWeave fell 2.7% and Nebius fell 3.5% in premarket trading on October 26, 2026, after Musk’s post, while CoreWeave’s bonds were already under pressure from worries about an AI slowdown and its balance sheet.
Will neoclouds go out of business?
Some probably will, or will be bought if Elon wants to put the fear of God into us well good luck I still might buy some debt this morning but that’s the point right now I was attacked by a National Bank that won’t investigate a theft or refund it. Gartner forecasts that by 2030 more than 80% of neocloud providers will no longer operate independently. Consolidation usually means new owners, not empty buildings, and the ones with their own power and long contracts are best placed to be the buyers. Why for the love of god hasn’t someone returned anything or even called me. BTW Google tried ripping me off again thank god organic search seems to be where the cooler heads prevail.
Source: Yahoo Finance, “Elon Musk warning on neoclouds: They will face ‘guppy-level death’,” Brian Sozzi, October 26, 2026, citing Musk’s X posts, Gartner and Bank of America. Quotes are as reported there. This post is an independent response and is not affiliated with Yahoo Finance, SpaceX, CoreWeave or Nebius.
Images: three original graphics by Kevin Katovic. © 2026 Kevin Katovic, all rights reserved. To license an image, email support@kevinkatovic.com.